Leaderboard
-
Guest_
FREEDOM14Points83,824Posts -
MikeTheThinker
FREEDOM8Points8,537Posts -
Lee01
FREEDOM8Points36,950Posts -
varooom
Resident Member7Points4,411Posts



Popular Content
Showing content with the highest reputation on 25/01/23 in Posts
-
Being in the trade myself I see this more than often. so many times people will come to me for brakes cause I’m cheaper than most - when they arrive I’ll take a look and the multiple times I’ve turned people away and returned the parts because they’re brakes are perfectly fine only to find out they were told at their mot/service that the brakes are almost metal to metal or something along those lines. I hate that people do this cause it gives a bad reputation for all mechanics and make us all look stupid. it’s not just dealers that do this, independent garages do this too!5 points
-
When mine was serviced at the dealership last year I got the exact same waffle about the brakes. When I collected my car, amongst the paperwork was a sheet attached which I assume was attached in error...it was a 'Successful/Lost Sales' section and in that section someone had logged that they had attempted to sell me some brakes and that I had declined. You know, if it was down in a 'Safety' checklist that's one thing, but down as being a 'lost' sales opportunity tells you all you need to know.4 points
-
Just had my Superb Sportline in for a service on Monday at Simpson's Skoda Preston, left the car with the dealer early morning to pick up late afternoon. A couple of hours in I got an SMS with a link to a vehicle health check, one item they were advising me about was "Visual check of brake pads rear" which I could choose to have corrected at a price of only £442.44 by simply ticking a check box and returning to them. Not exactly the bargain of the century so I didn't bother, I was also somewhat surprised that my 18,000 mile car should need this kind of attention. A little later on they called me to discuss (AKA twist my arm, it's brakes after all so safety related!), I asked how worn the pads were, "About 15% sir", obviously my response was that this hardly constituted need for change. "Ah yes, but the problem is the disks, they are pitted" "Really, they looked OK to me" "Well its on the inner face, not the face you see from outside, we do a visual check on it" "OK, well thanks for letting me know, the car's being sold soon so I'm not looking to spend money on it. Leave it" As I'm selling the car I decided to change my wheels over last night from my winters to the proper set, while doing this I decided to have a proper look at the discs. This was quite difficult as the shroud and the caliper obscure most of the inner disk face but I could just about see up between these and the disk (with the wheels off) and as far as I'm concerned both disks were A1, I'd be really surprised if they could see better as it's my understanding that they don't even remove the roadwheels during a service these days. Now call me a cynical old git if you want (hey, less of the 'old') but I can't help thinking that this was based more on something on their checklist than any assessment of my vehicle and I suspect they trot this out to most if not all customers as a money making scheme. They are obviously not going to catch me out with this as I'm quite savvy with automotive related issues but I do wonder how many poor customers do get caught out who are not mechanically oriented and of course being brakes they panic and immediately sign the work off. Why should owning a car be such a minefield? Has anyone else had similar experience? I'm also struggling to come to terms with a price of thick end of £450 for a couple of disks and a set of pads even top quality items would come it way below that and even if I did it myself taking way more care than they would I'd struggle to take more than an hour, I wouldn't even bother putting the car on the lift for that, easy enough to do on a jack and axle stand. I must also add that it is mainly the behaviour of Simpson's Skoda Preston which is responsible for me selling this car now after only 18months of ownership, they have made owning this an absolute nightmare, obviously I'll not deal with them again but it also means I'm done with Skoda now, at least from the point of view of owning a car where I have to deal with a dealer. My previous, much older, car was a much better ownership experience (and what lead me to look at Skoda when wanting a newer car) as I only ever had to deal with a specialist not main dealer.3 points
-
3 pointsWasn't sure where to put this, but thought it would fit nicely here, due to... oh, well wait until 3:52...3 points
-
Why do you have to be so objectionable! I have always found Toot to be most helpful on this Forum and would sooner take advice from him than someone like you . It is obvious Toot knows his stuff regarding engines etc. But as you apparently cannot grasp that. Perhaps something to do with your background and lack of engineering experience.3 points
-
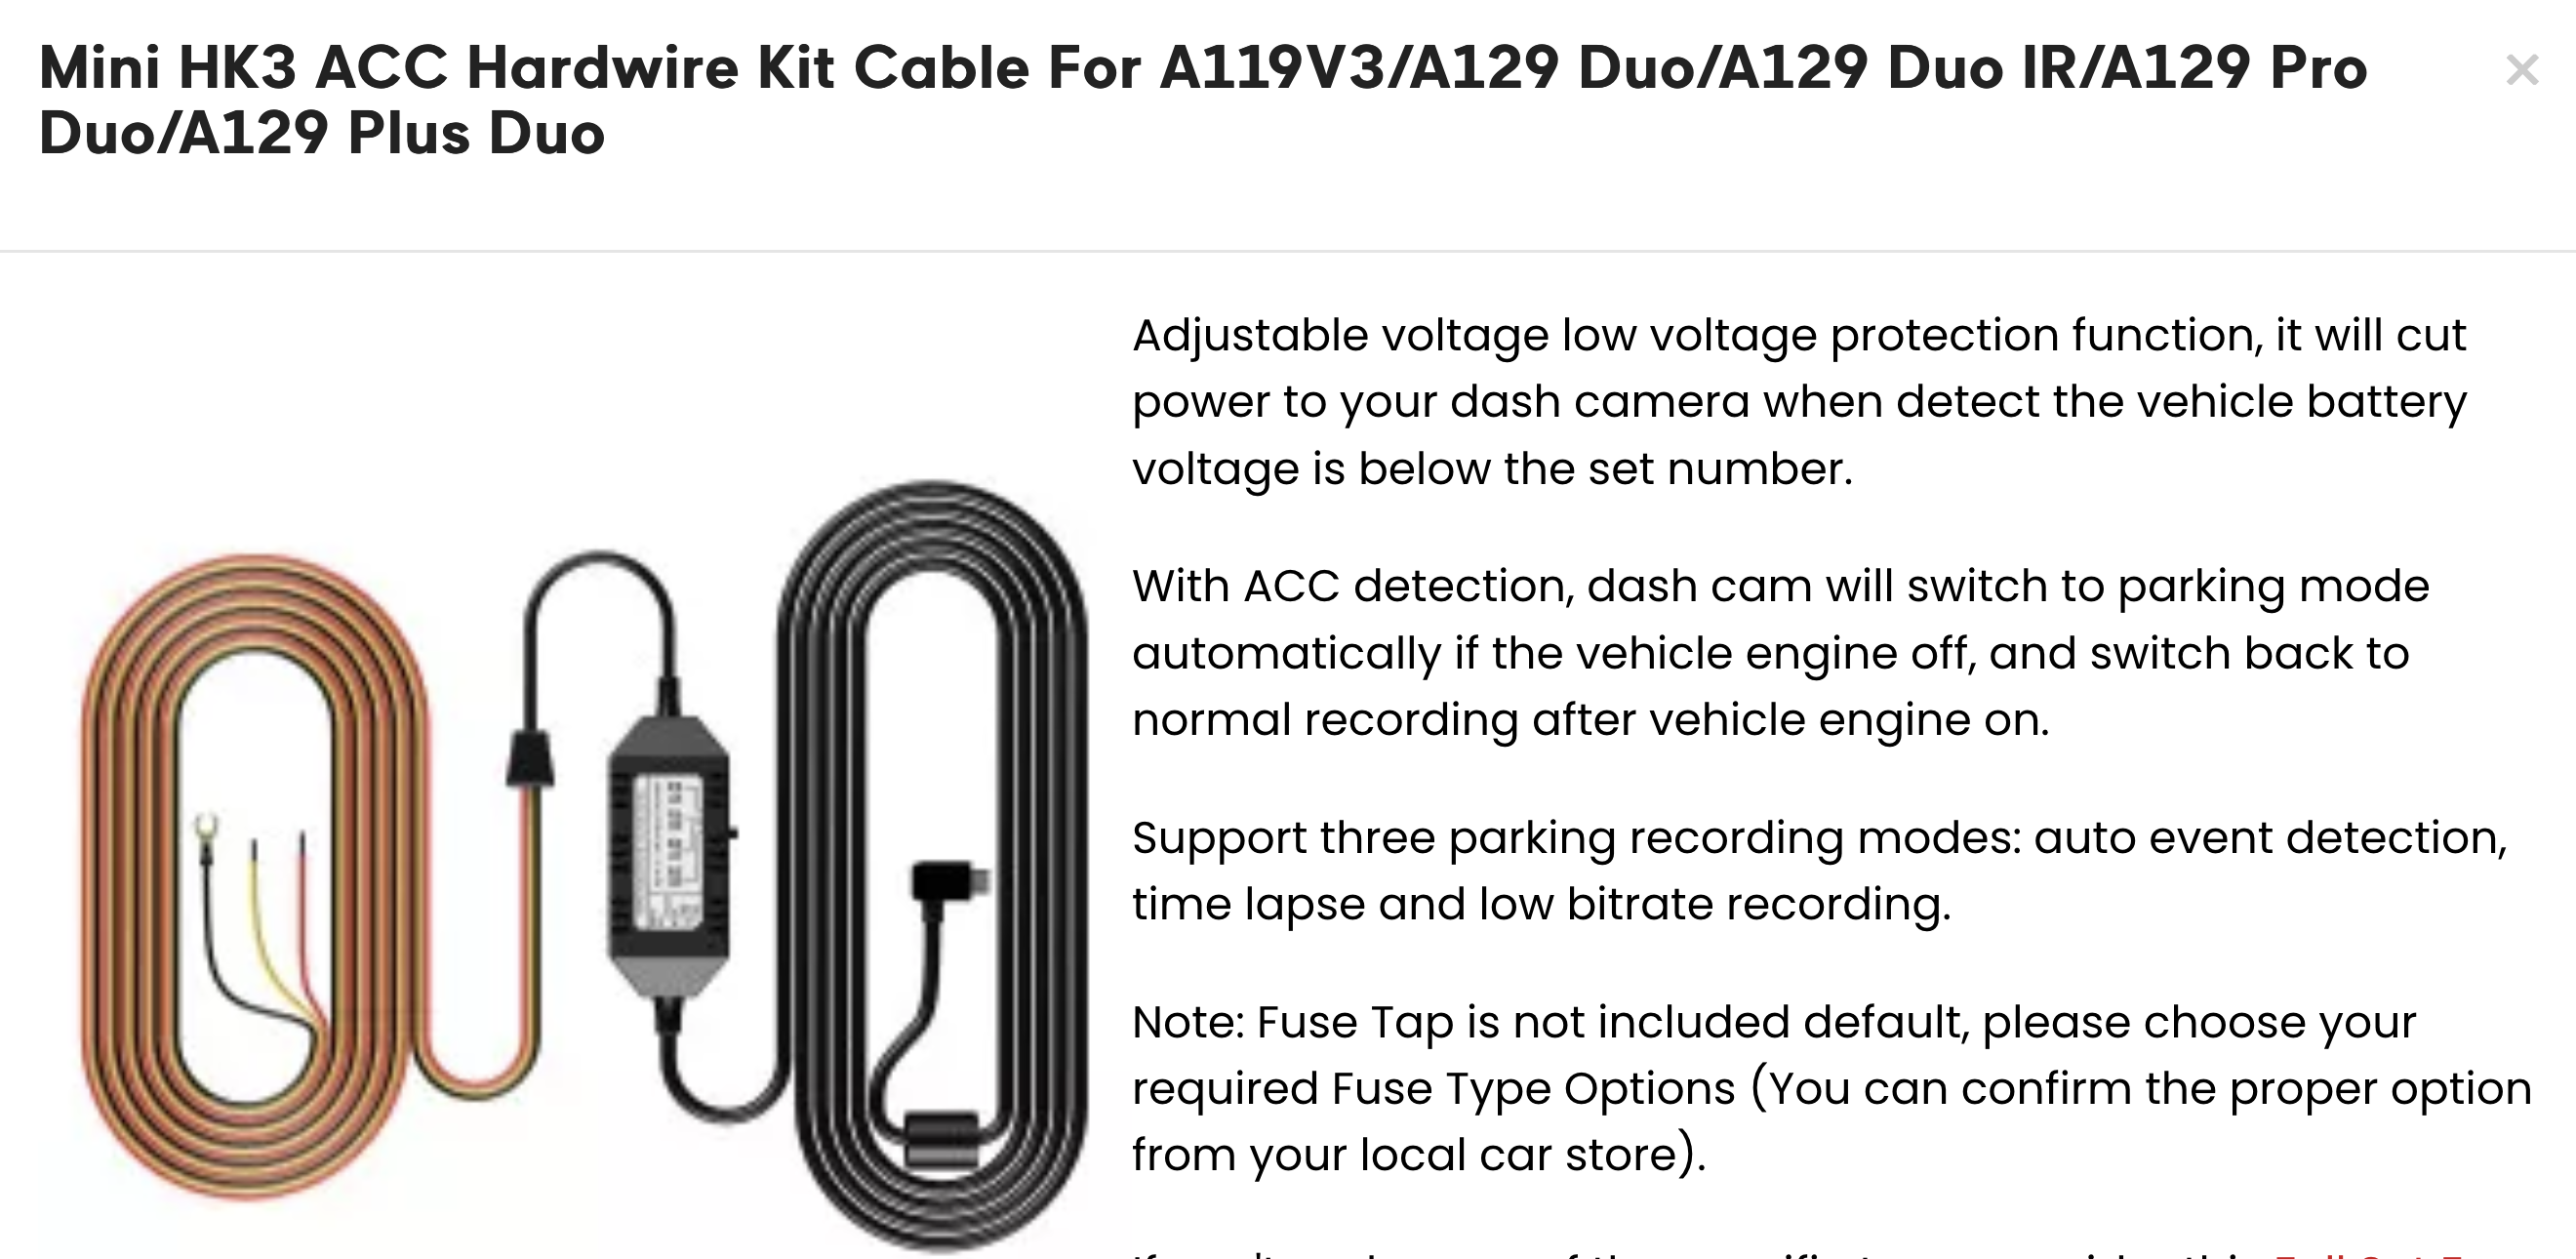
3 pointsUSB is an added option not standard. Someone got asked if they wanted it said no couldn’t see the point then got a dash cam then the penny dropped had to hard wire3 points
-
2 points
-
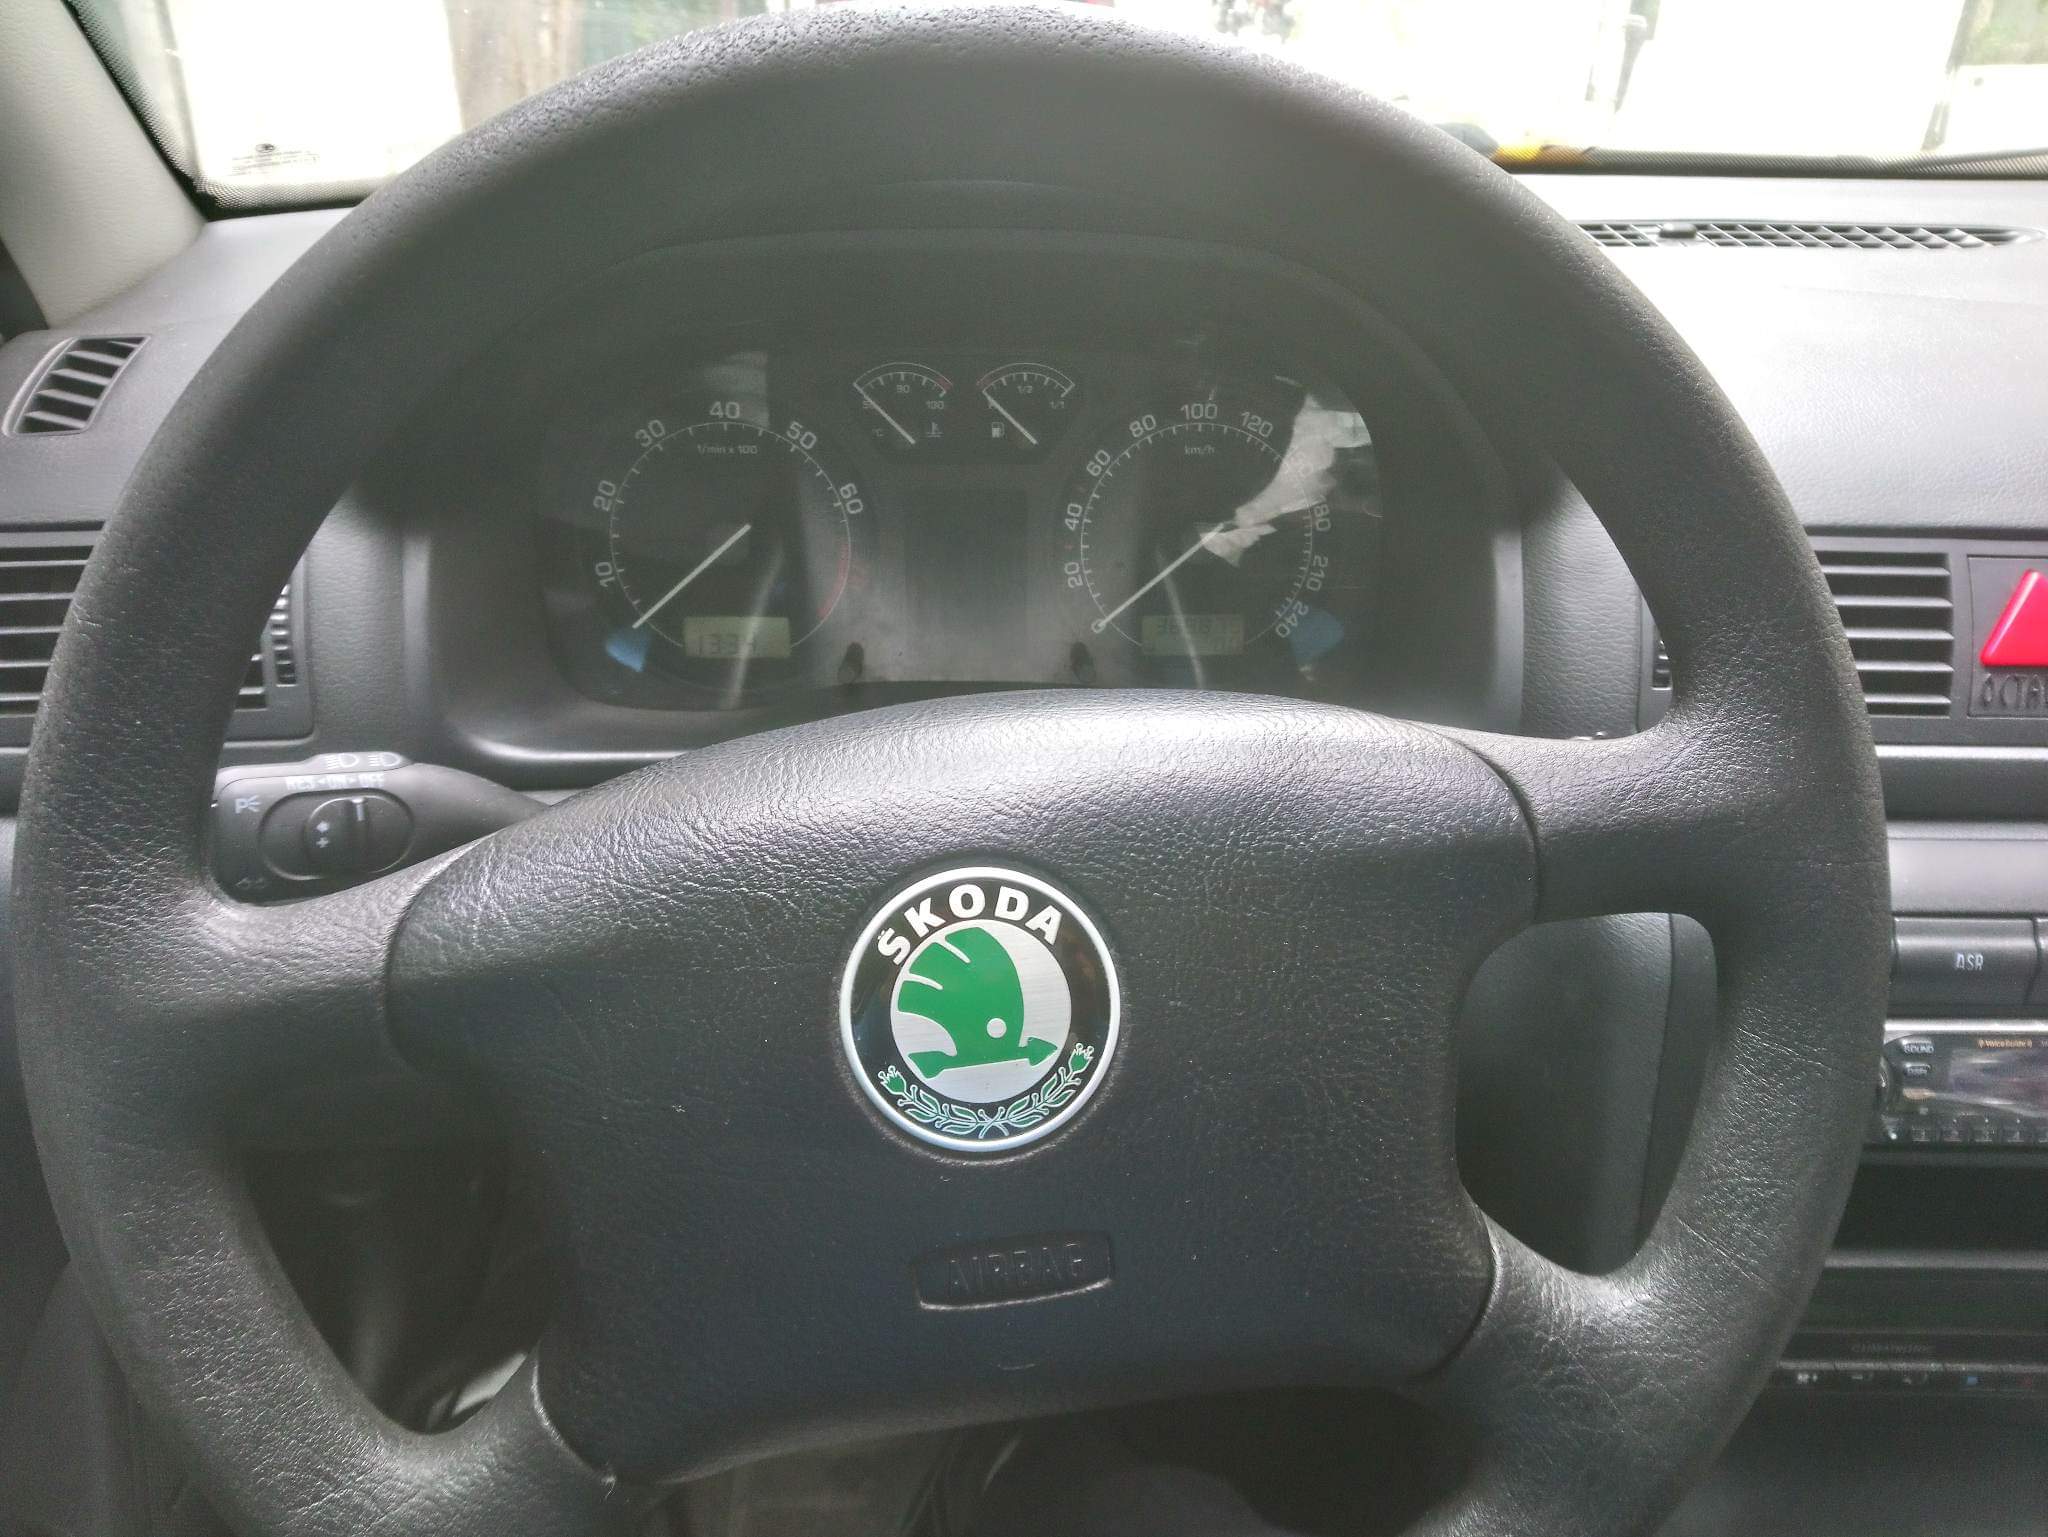
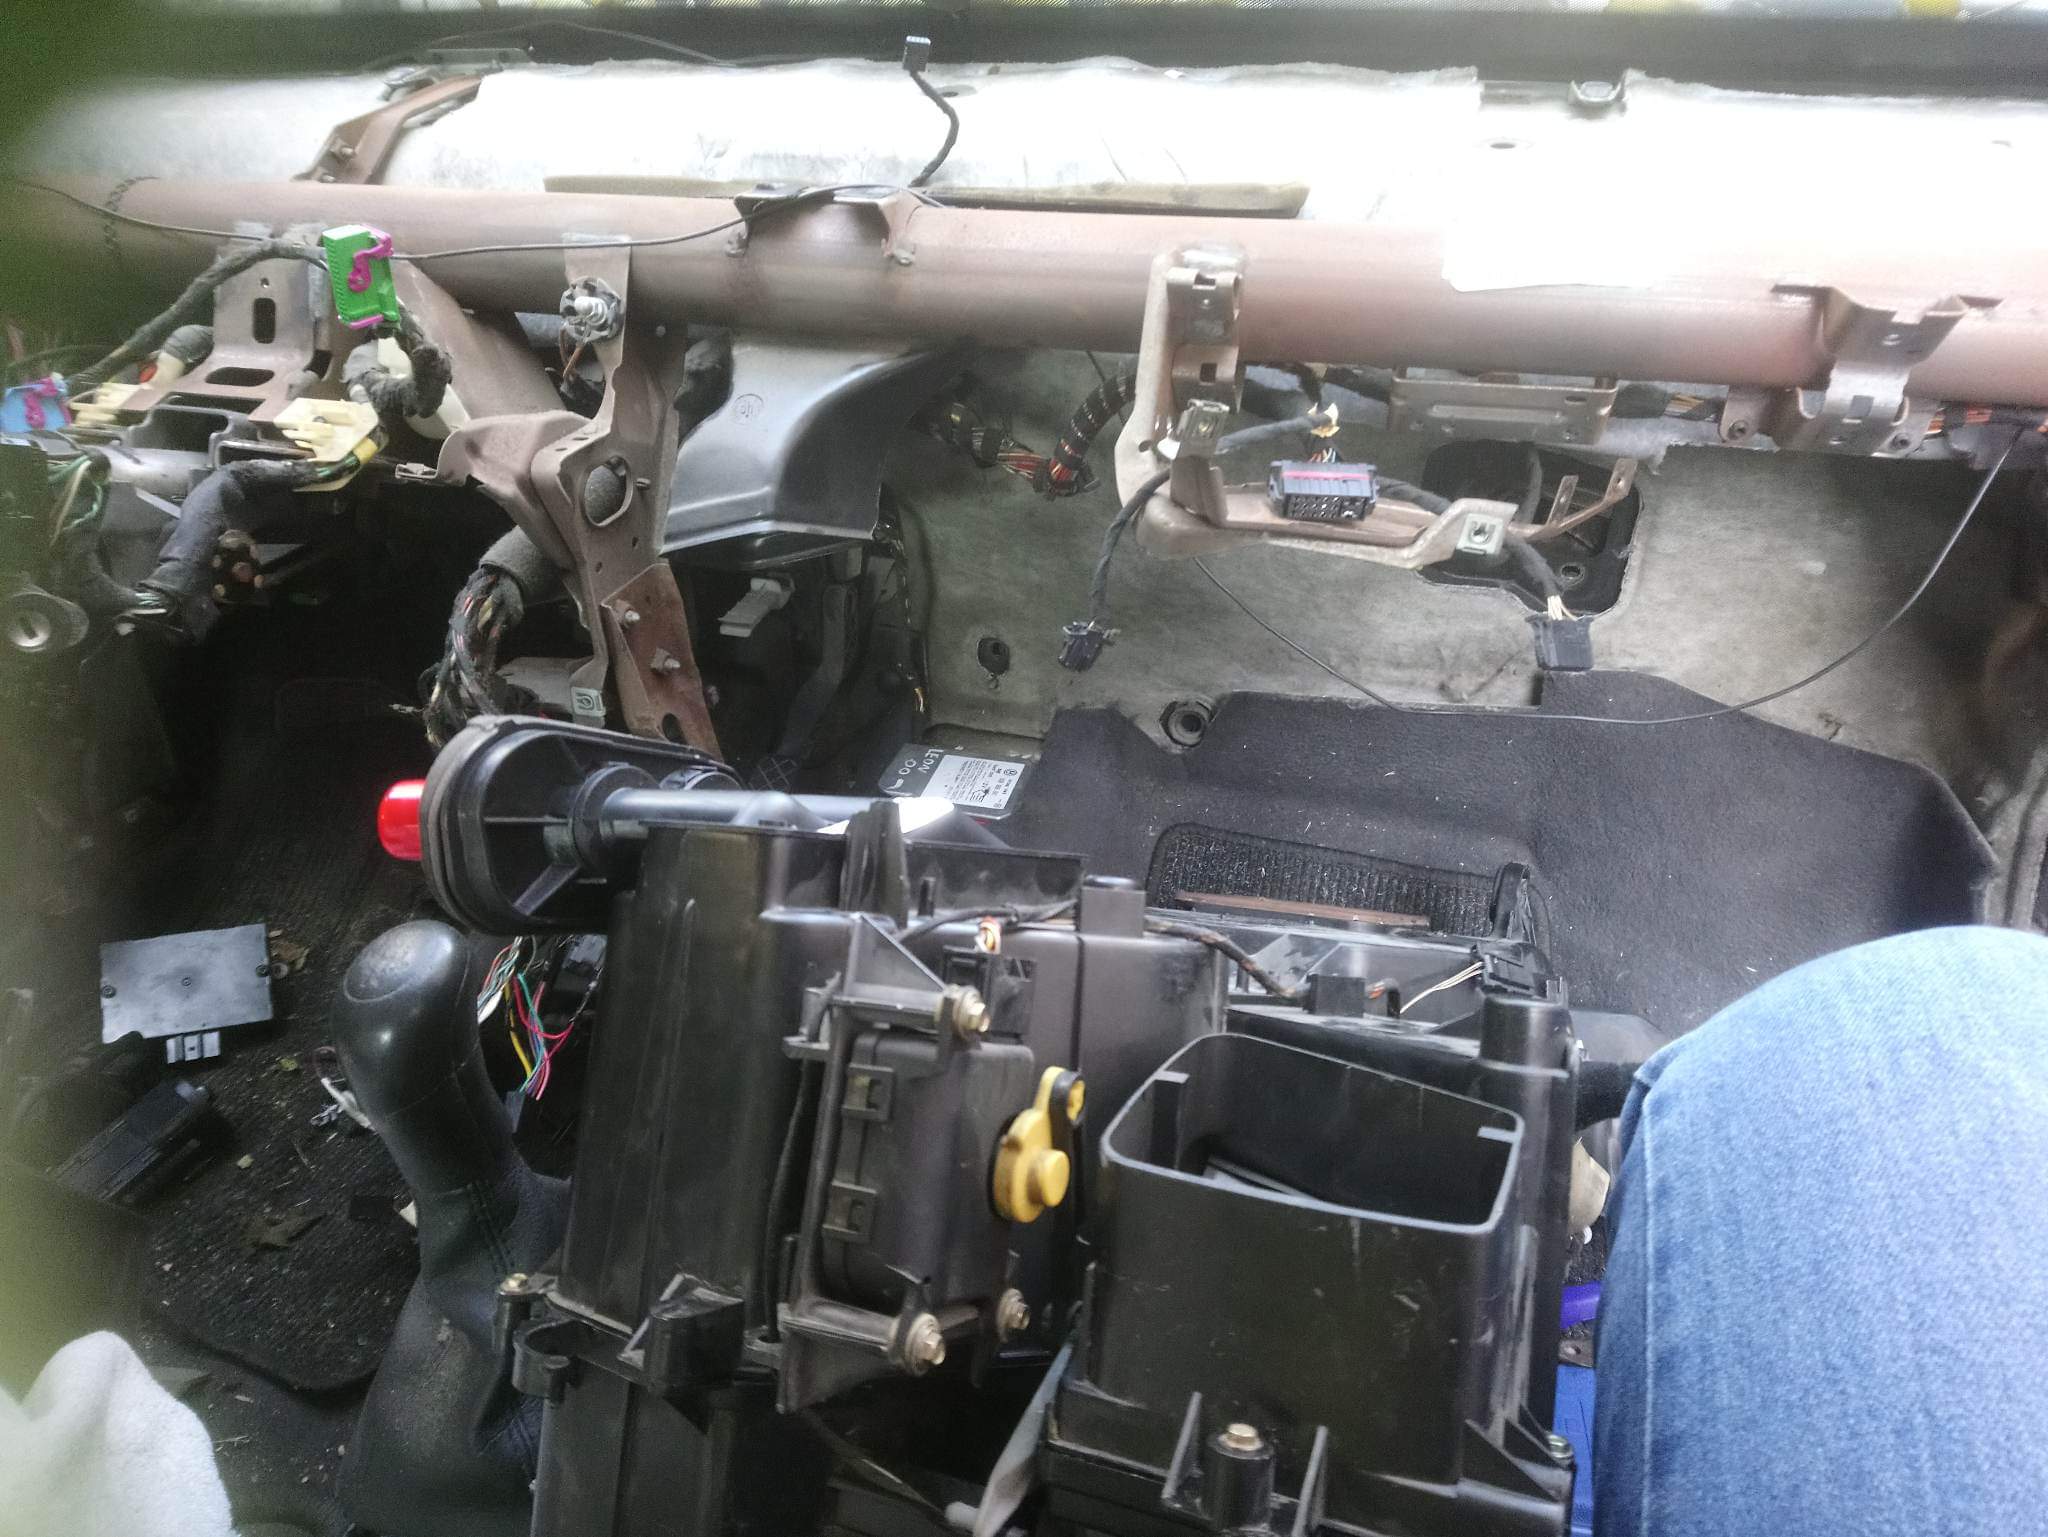
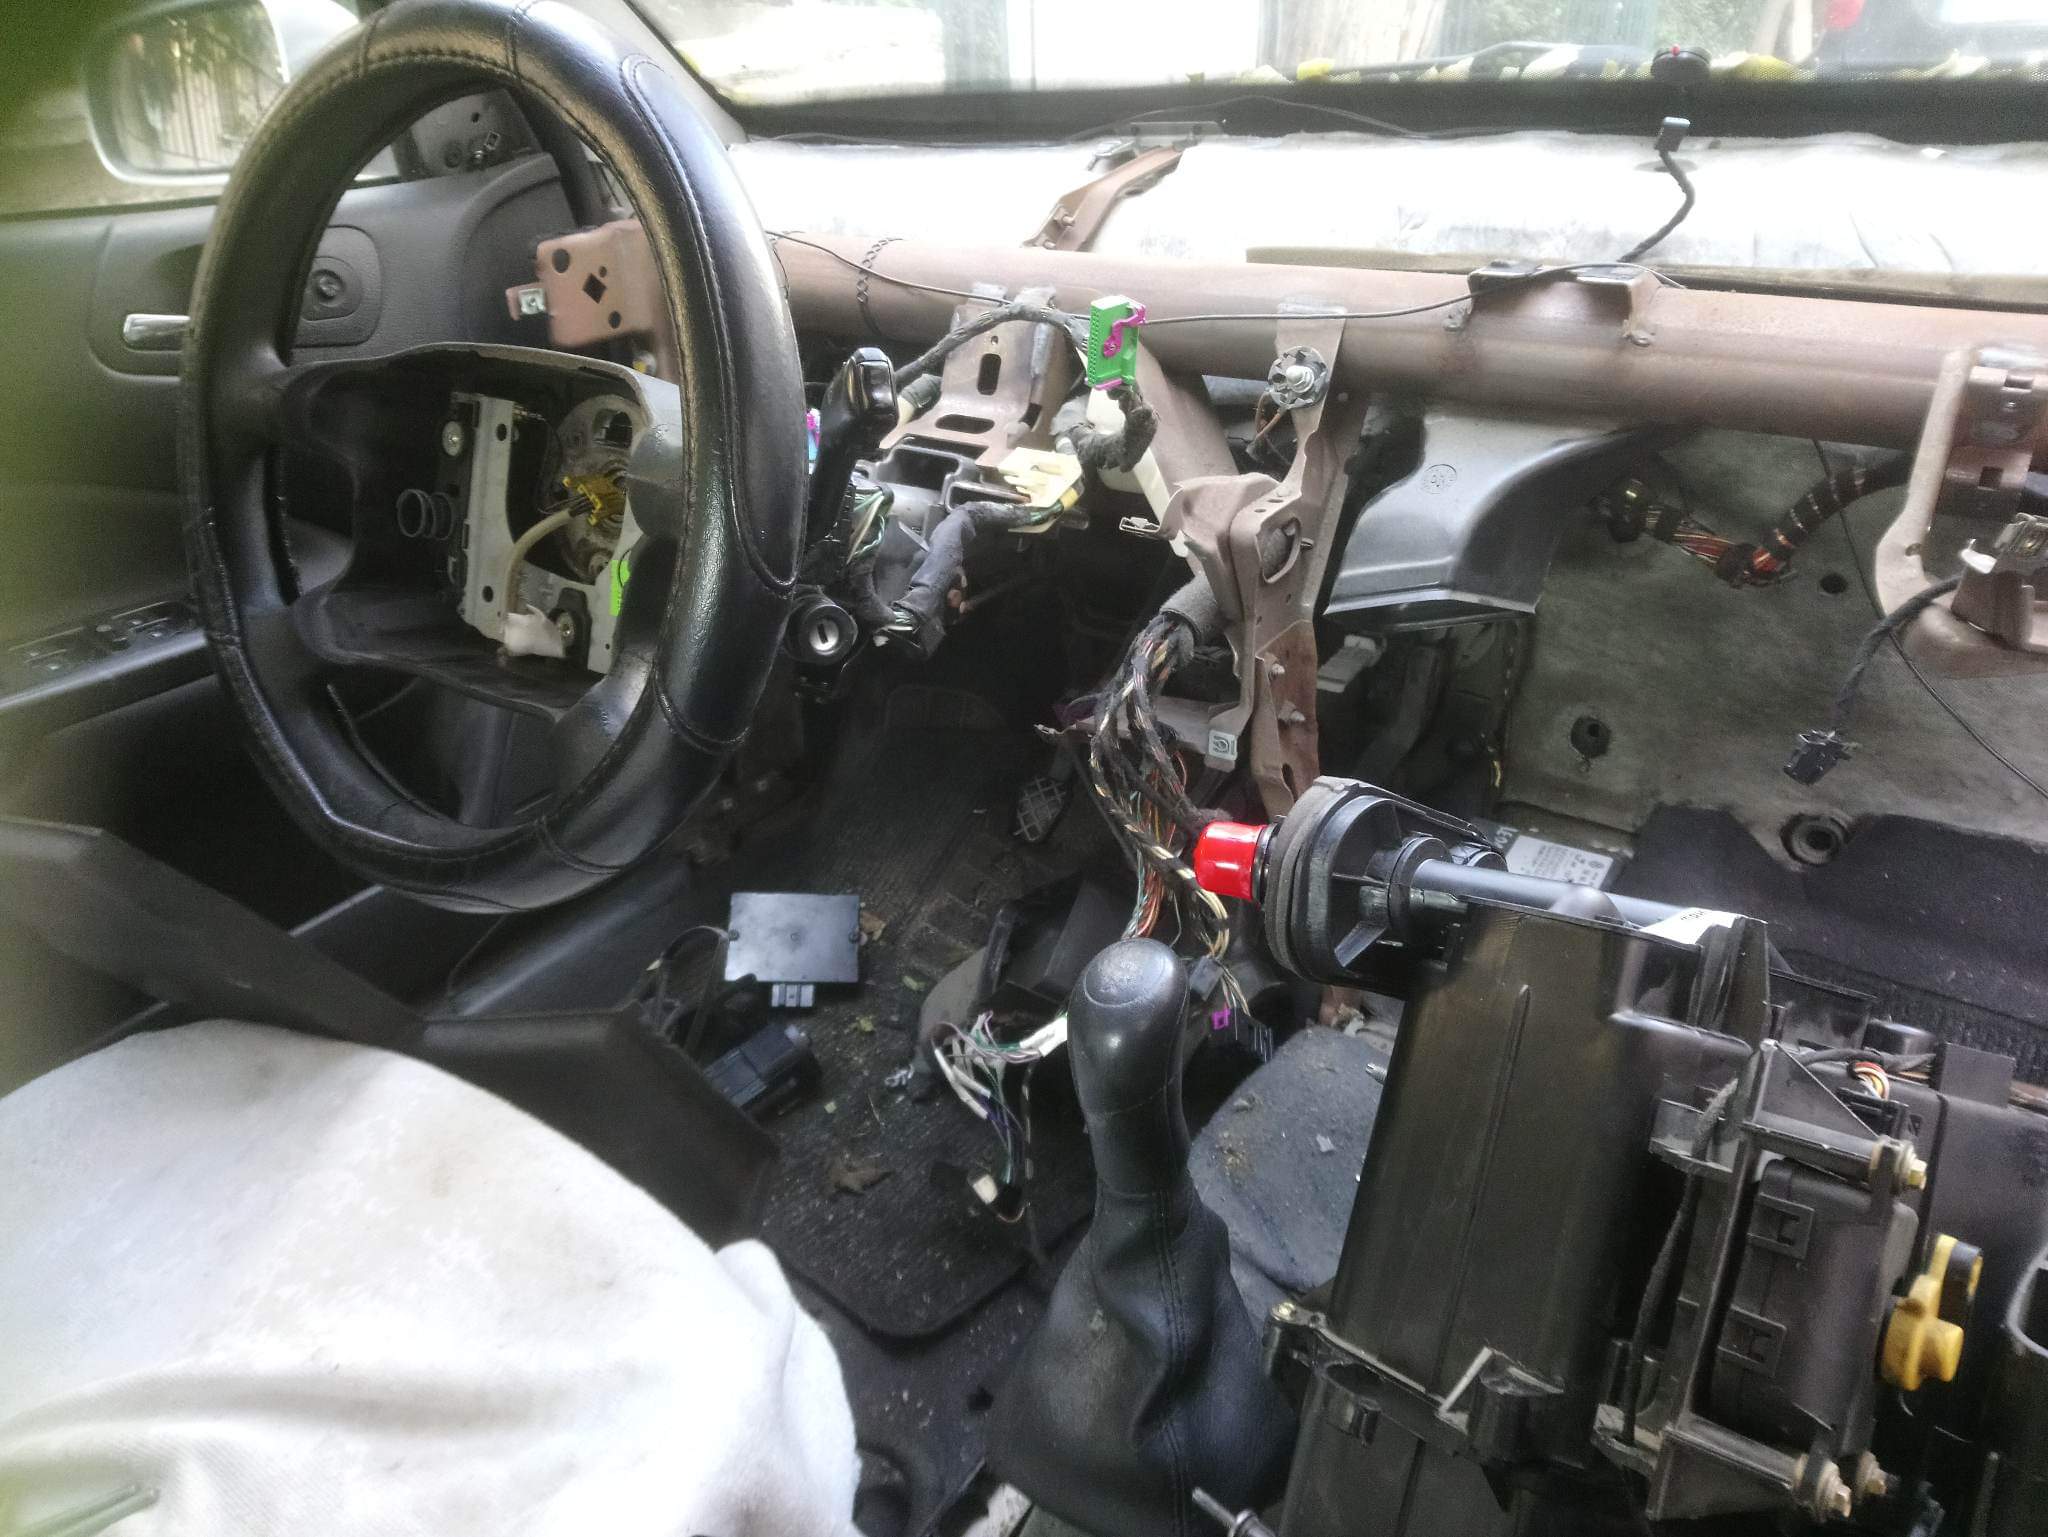
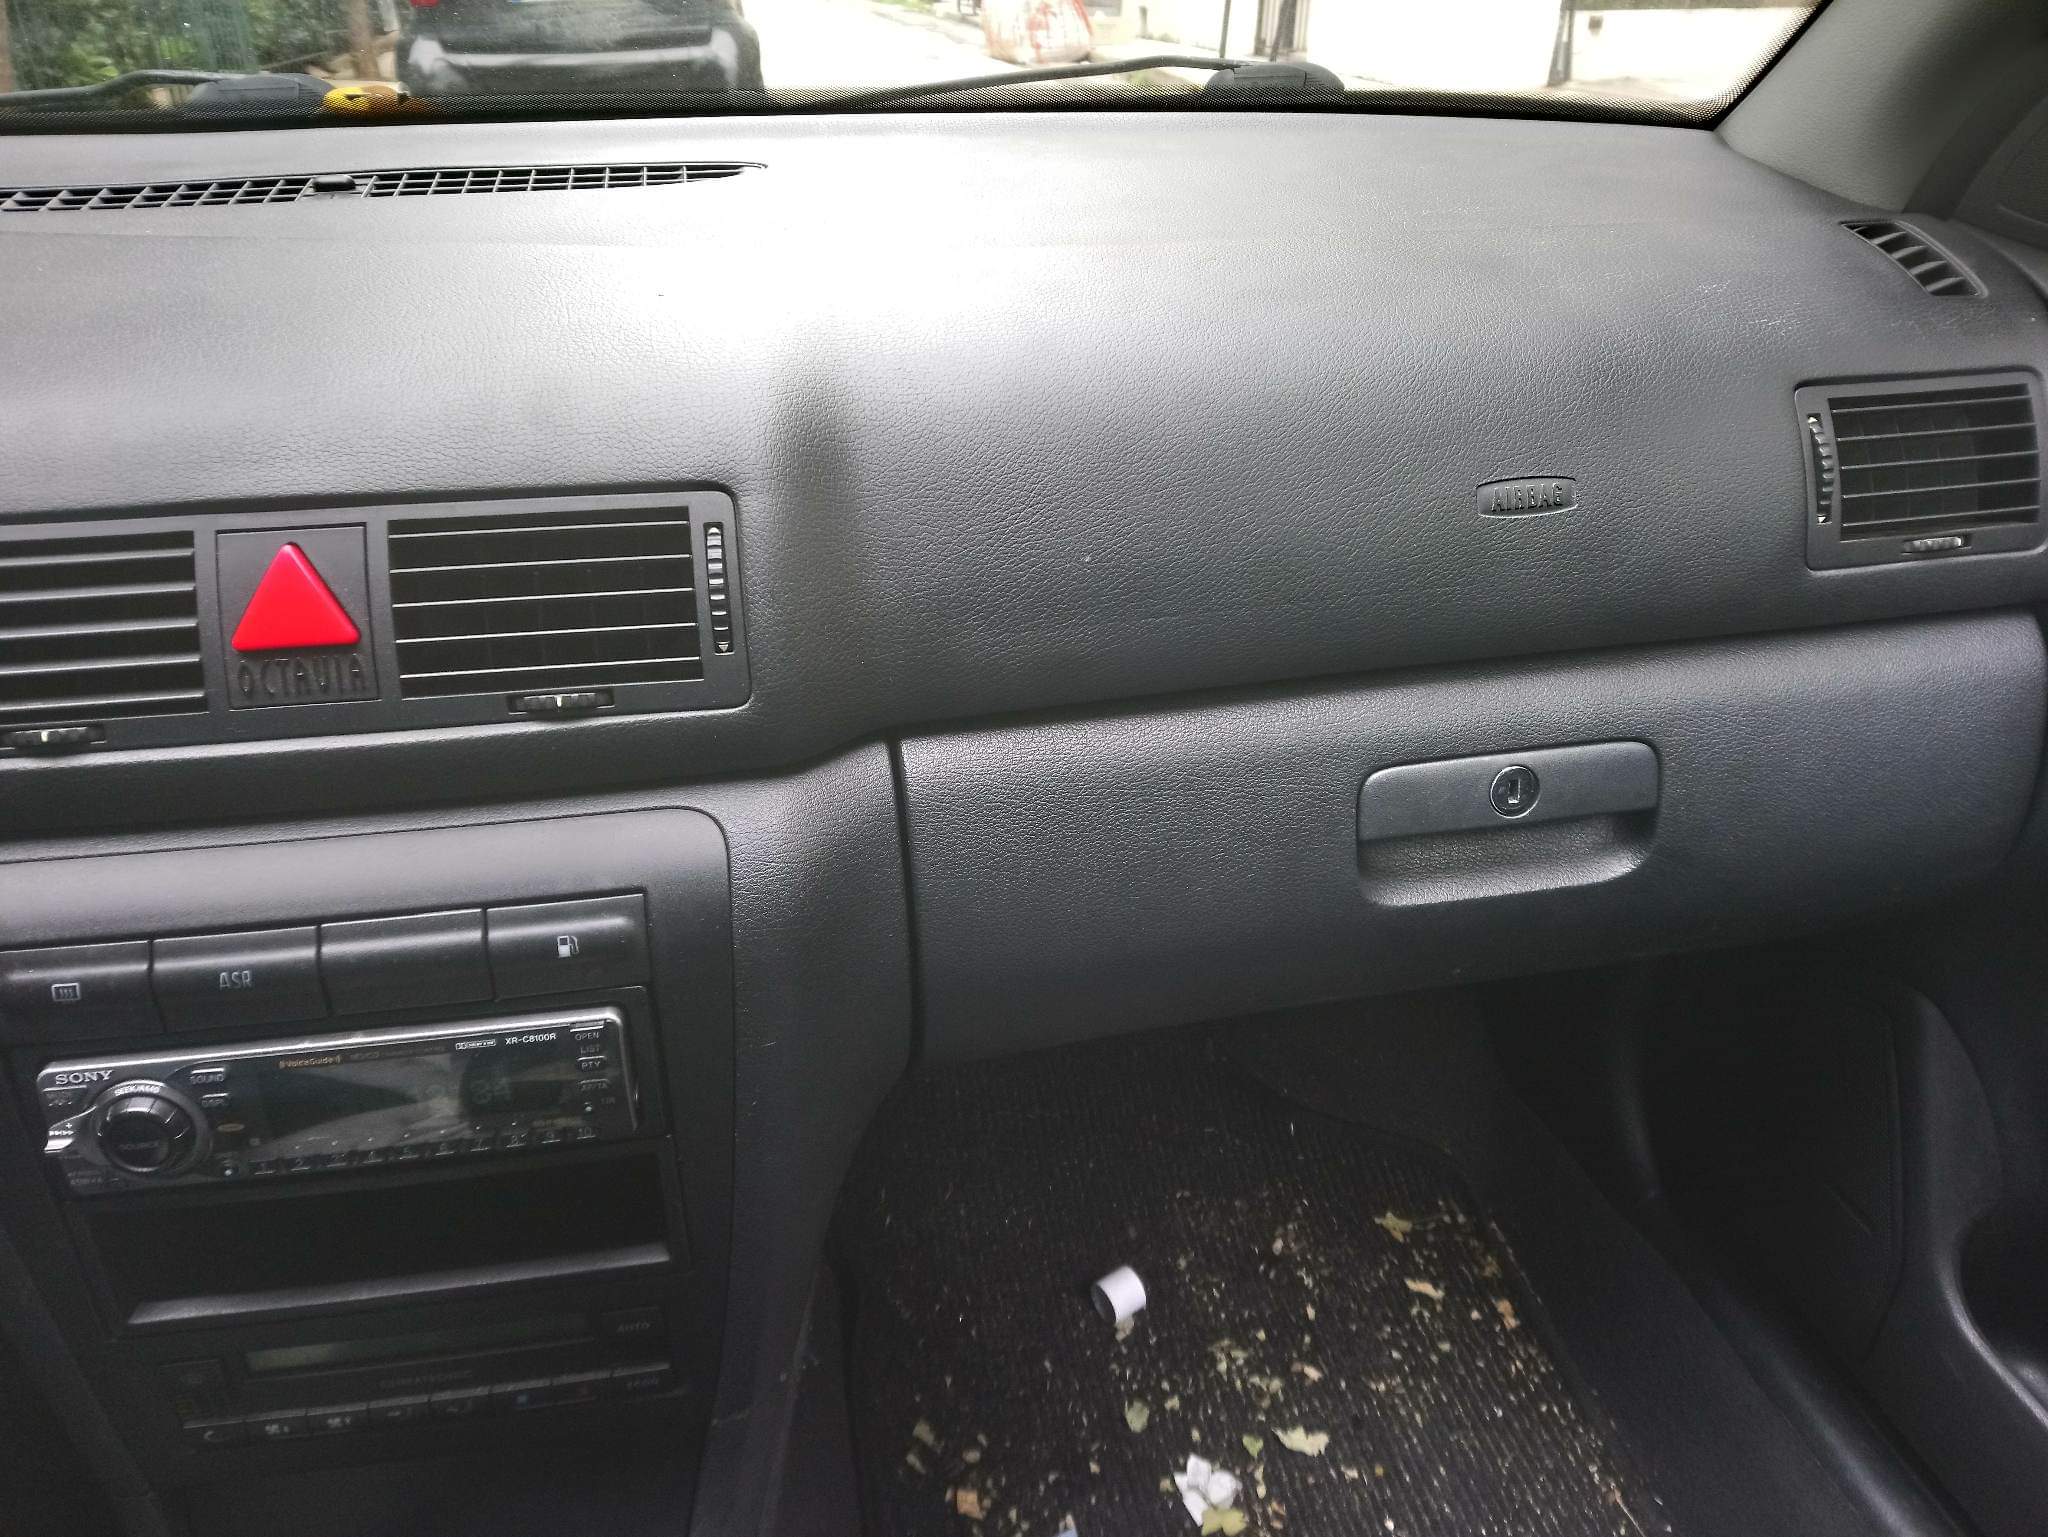
2 pointsSome more progress From this point To this state A plus: since the whole dash was out for replacement (airbag deployment) I decided to add the cruise control. The 1.6l petrol has the ecu loom ready (like the diesels) so only the stalk loom was needed and with no dash in place - piece of cake! Technically, from this point on, the car can return on the roads. But it needs some more TLC. The best yet to come!
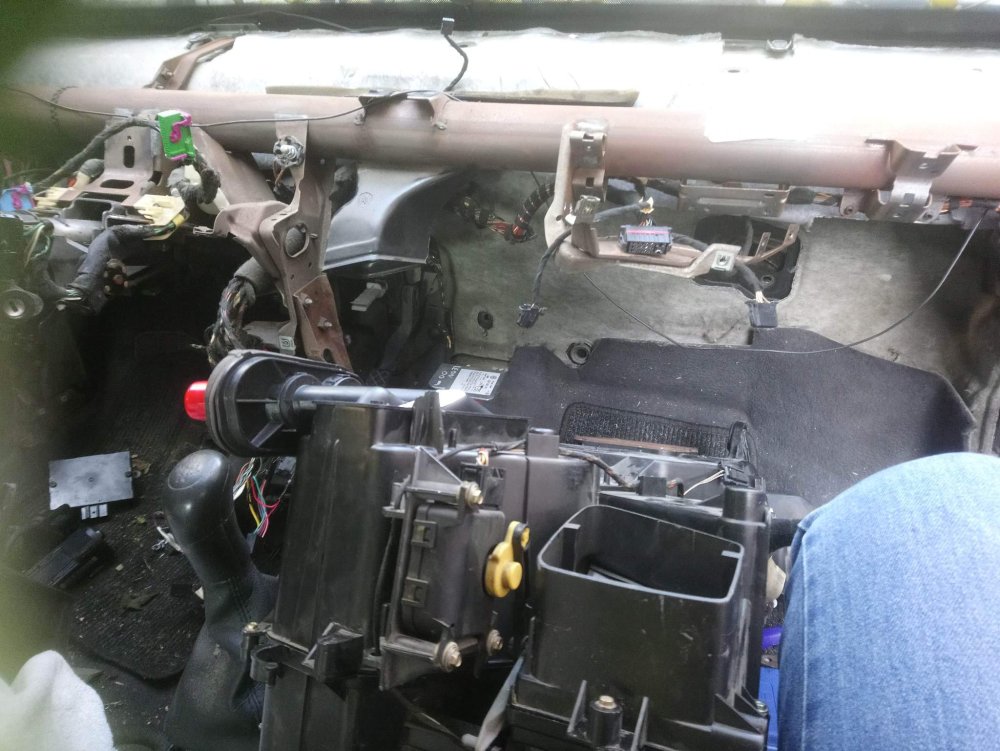
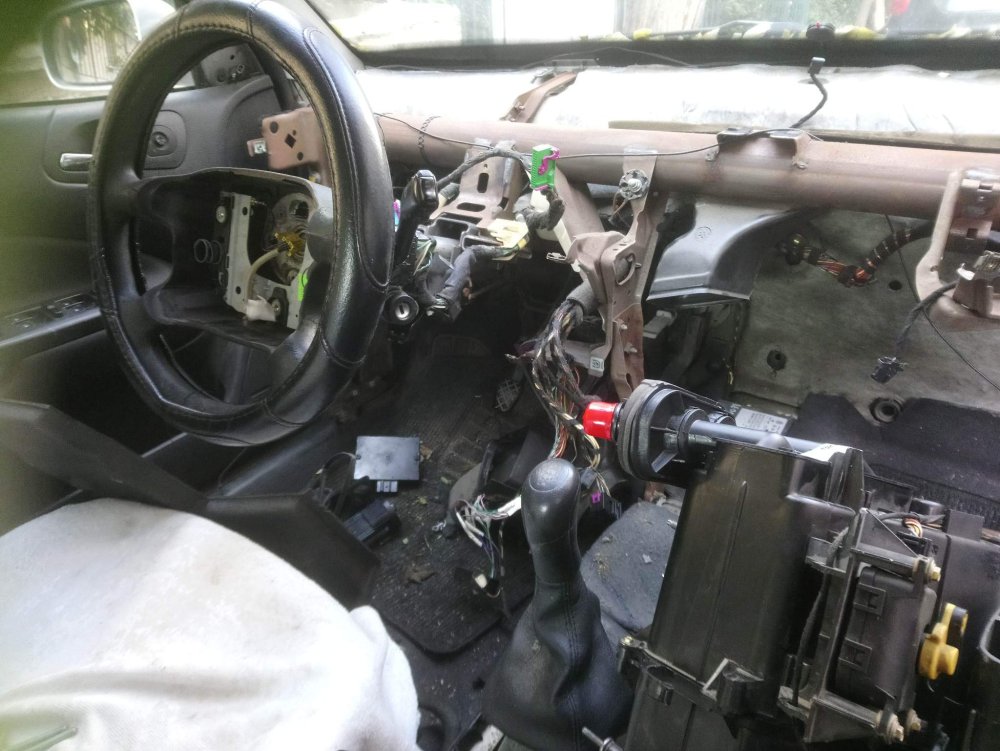
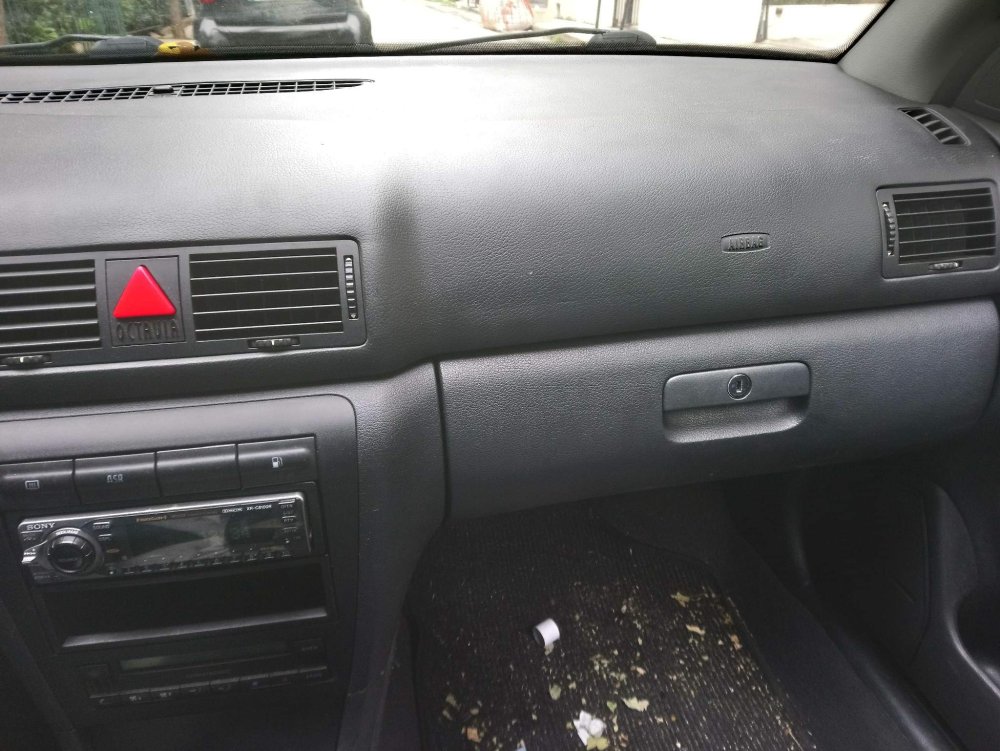 2 points
-
2 pointsWelcome. What ever it cost to repair is surely less than the cost of buying another car.2 points
-
They catch many. 15% was a good one. Often they are claiming 80% worn when not even 20%. The Service Desk staff have no idea what the 100% measurement would be. Interestingly there are usually Skoda Approved Used Sales Cars outside with more wear and and pitting that are service and PDI'd ready for the next owner.2 points
-
2 pointsWelcome. How many miles has it done. What does the Full Service History show as been done. Maybe not this, but. So my guess. The VAQ Diff will not have been serviced at 3 years / 30,000 miles. So that is outstanding and needs done, so that the car is Serviced to the Manufacturers Recommendations, Guidelines or even Schedule. Not part of a Service Plan, probably not in the 2 Services that Arnold Clark gave you in the deal. Needs doing or the Warranty they gave might mean they are paying out if the VAQ fails. PS. Now on Mk4 vRS TSI's some Dealerships are saying due at 2 years. But ARNOLD CLARK staff might not know about that anymore than about @ 3 years / 30,000 miles. So a FULL MAIN DEALER SERVICE HISTORY, just not a history as serviced to the Manufacturers Recommendations, Guidelines or even Schedule. From the Mk4 section. http://briskoda.net/forums/topic/509911-vrs-owners-cars-with-vaq-front-diff-a-question-on-servicing-and-what-you-are-being-told-at-skoda-main-dealerships2 points
-
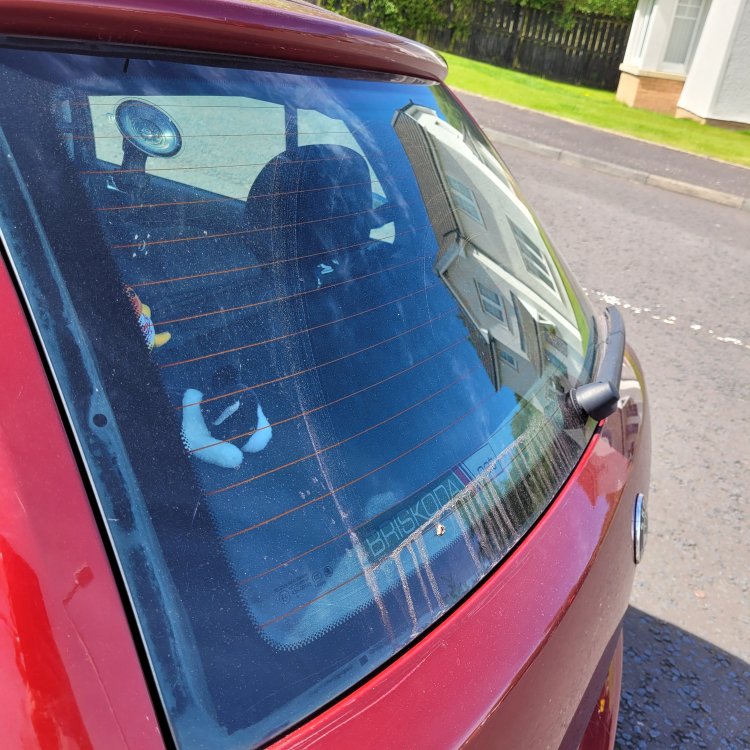
1 point1 point1 point1 pointIf it's the same "stubby" hatch as mine then I don't think that's removable, and is part of the whole tailgate.
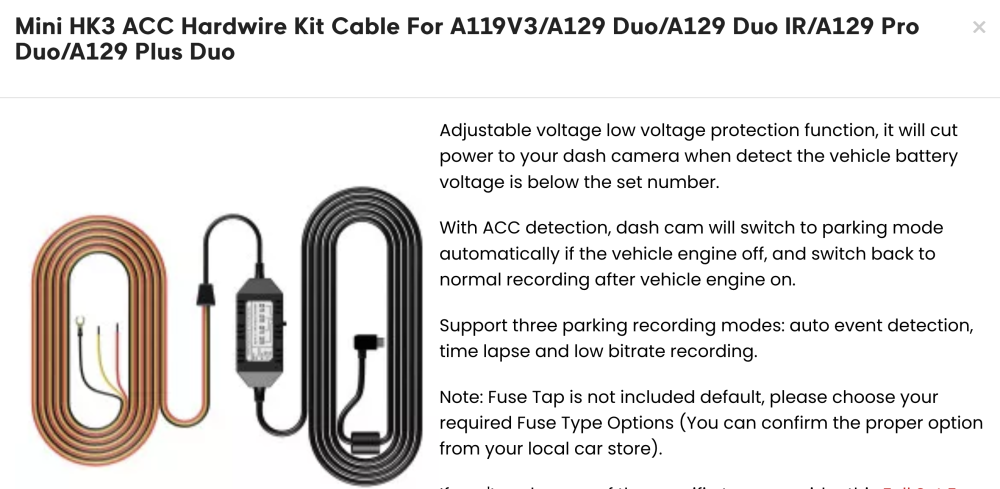
 1 point1 point1 point1 pointNow I have a few hundred miles on them, I can say I’m really happy with the Conti All Season tyres I had fitted before Christmas. Grip in the wet and dry are excellent but the biggest improvement over the P7’s is the reduction in the tyre roar noise in the cabin; I estimate it’s down by 70%. Also I haven’t really noticed a reduction in MPG either.1 point1 pointGlad I searched before posting! Surprising a channel like the mighty Carwow did a vRS feature.1 point1 pointI gave ours a tiny squirt with some dry silicone spray and that solved the issue of the NS catch not fully popping out and that, in turn, solved the problem of it not fully closing.1 point1 pointWe did, it’s no that kind of noise I don’t think. I got the last one checked and forked out for a bearing and the effing thing made the same noise first time out on a M-way 😂1 point1 pointSorry Gaz, seems to go up and down uniformly with speed and no apparent change on cornering. Hard to hear on side or A roads. The missus could hear it yesterday so it’s no just my rubbish ears!1 point1 point1 point1 pointNo, the kit provided by Viofo has 3 wires: 1 ground, 1 permanent +12V (only useful if you use parking mode) and 1 wire for non-permanent +12 V (contact/engine ON). This kit only powers the front camera. The back one connects directly to the front one for power supply and for data transfer to the SD-card.
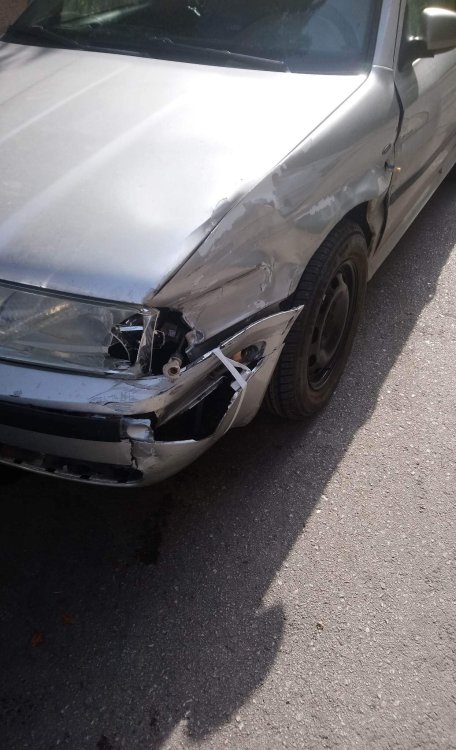
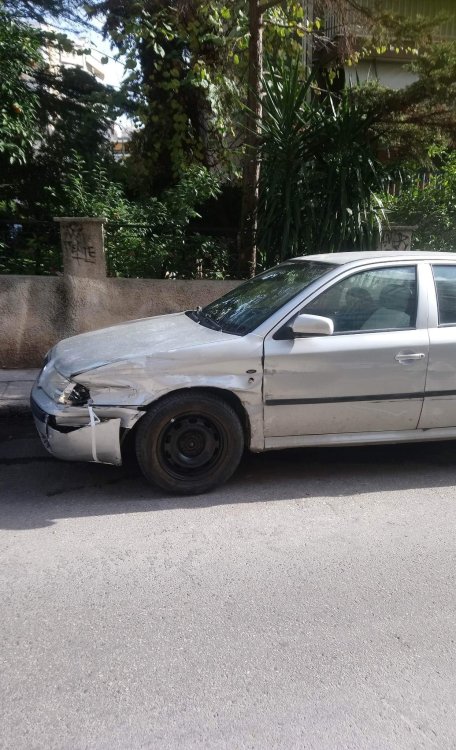
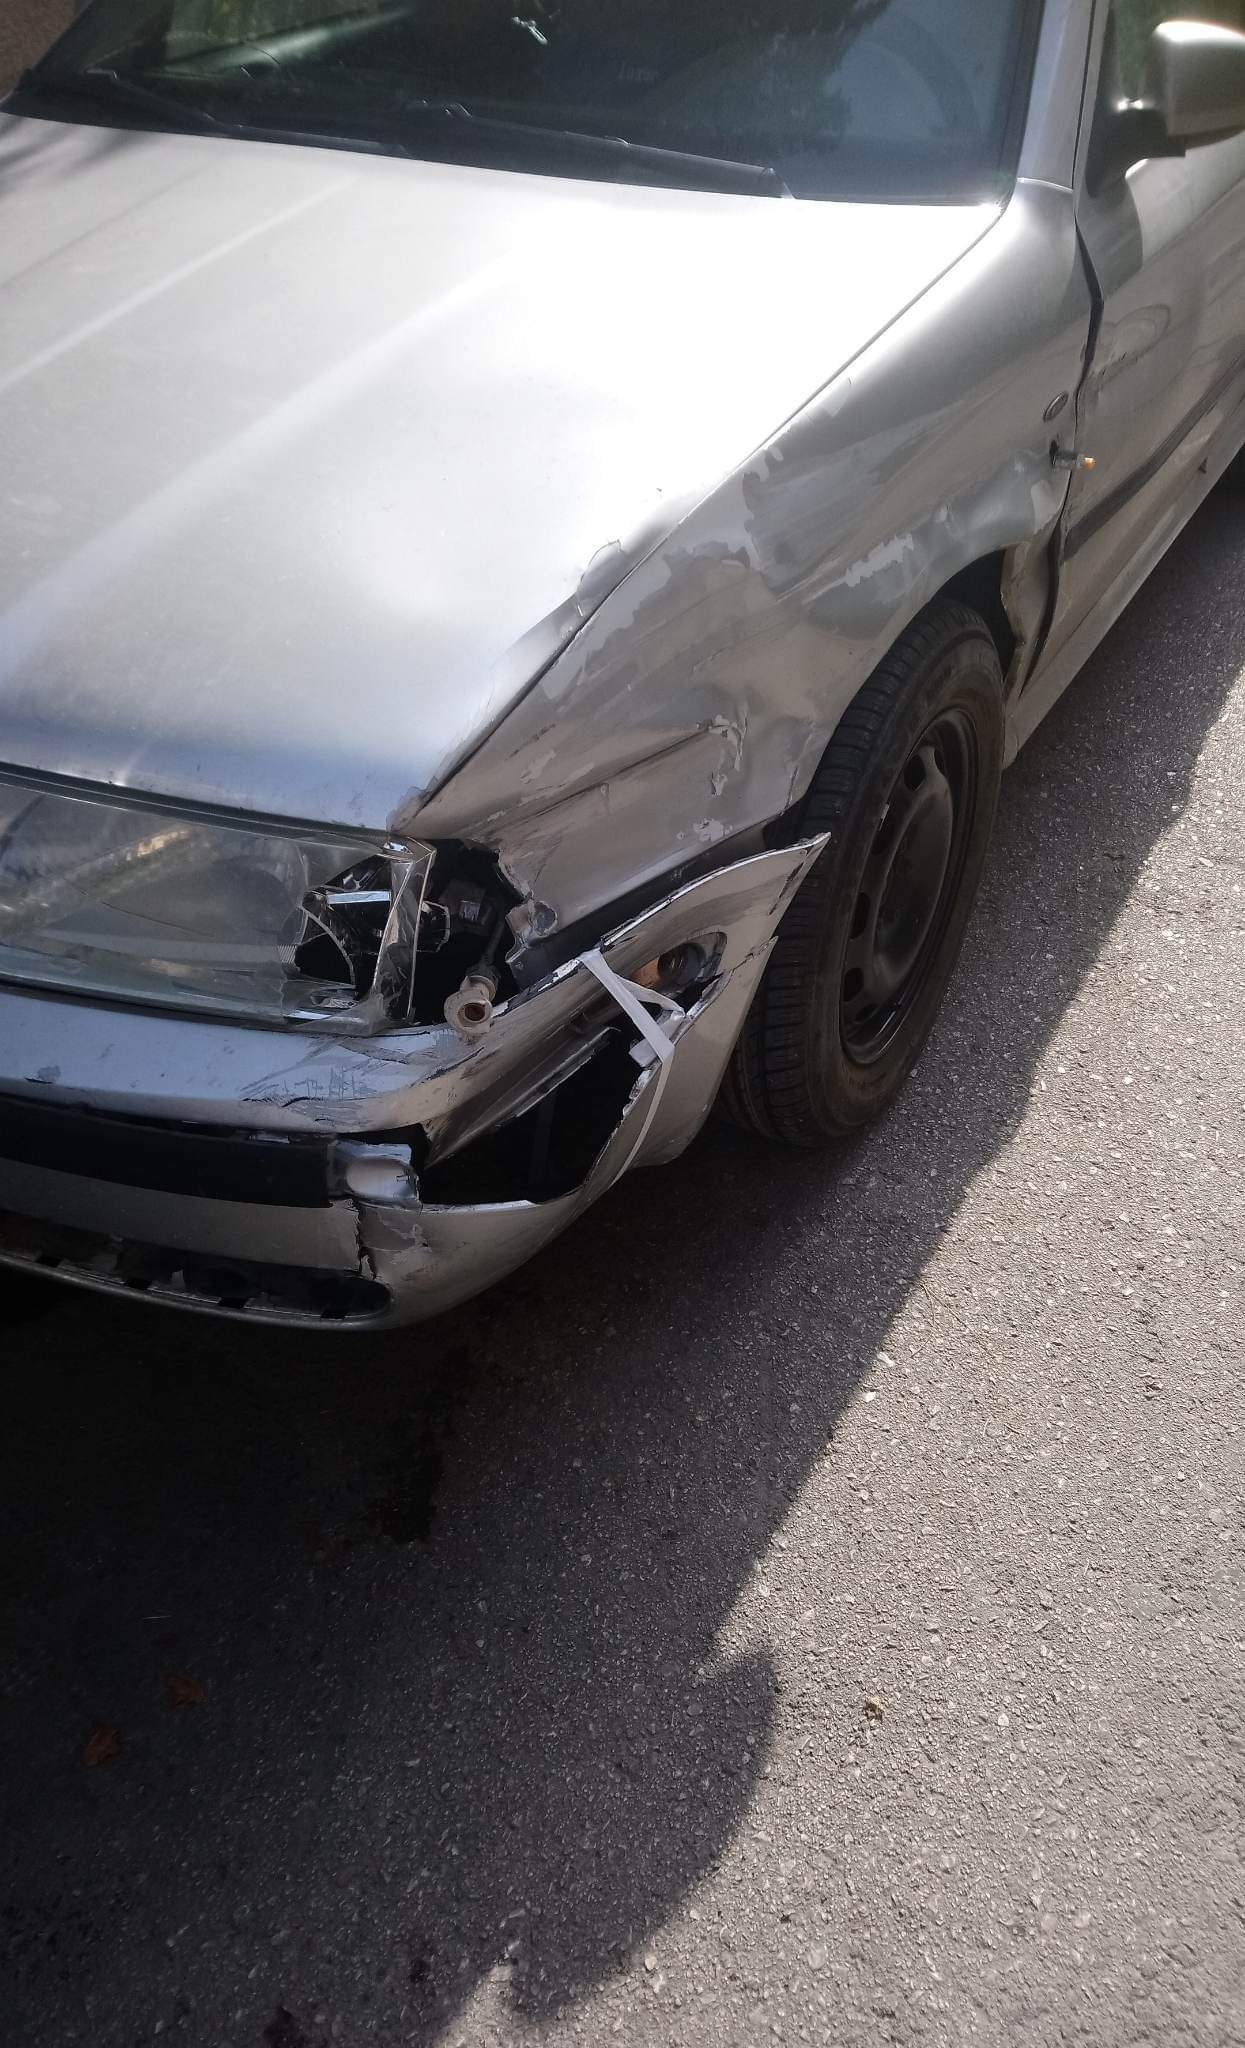
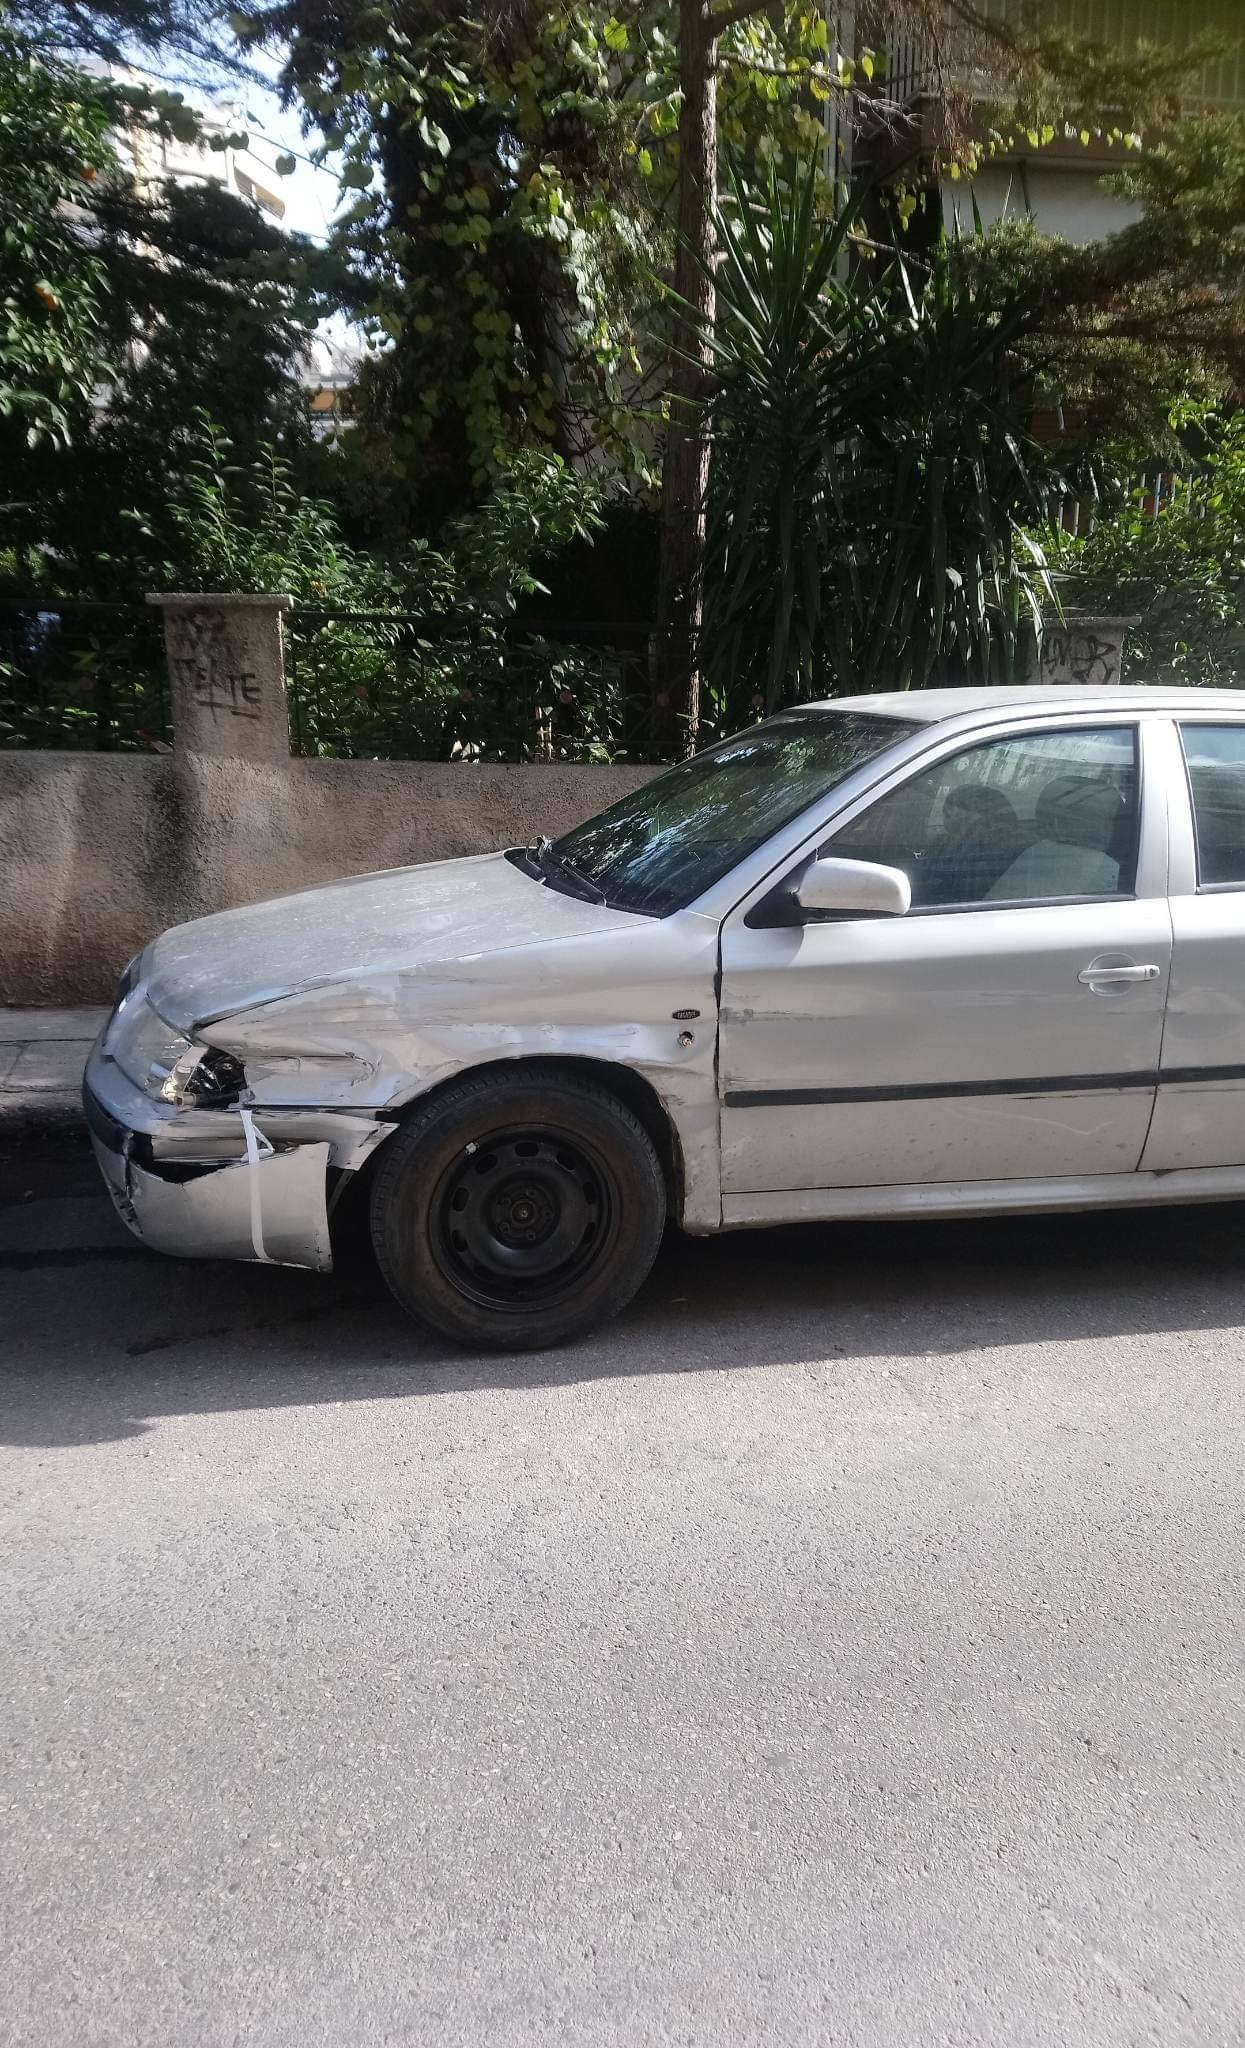
 1 pointYou have absolutley no idea of what is involved in changing the cambelt on a 1.5tsi. Who are you to say it's silly? The price in John 'o 'groats is going to be different to the price in Mayfair. I'm impressed by how expert people think they are who have zero experience, zero information, but think themselves qualified to say something is silly.1 pointThanks for the info - the Felicia is a 2000 car, it's our 2 x Favorits that are 1995 - I've changed my profile, sorry for confusion! But only 5 years difference! We haven't had the Felicia very long. We had been looking for ages for an estate. We'll try what you suggest and fingers crossed!1 point1 pointMake sure you have your VIN stored in a text file ready to copy/paste into the site. This will then allow it to filter files to your motor. You should also be able to download you build codes (PR Codes) that will allow you to find parts just for your car fitment.1 point1 pointWell, my nephew decided to move on and let the injured Octy at my hands! Practically, the car should be written off. It has 370k kilometers on the clock and the damage is costly, including the airbags and seat belts. But the engine has a lot of juice left and I'm quite stubborn to give it up. So, I will try to restore it and even better, to make some mods. I definitely will need some help so can I count on here? Hope not to be boring, asking all these questions. It's one more Skoda saved from the scrap yard, returning on the road. It's a reason to be happy, isn't it?
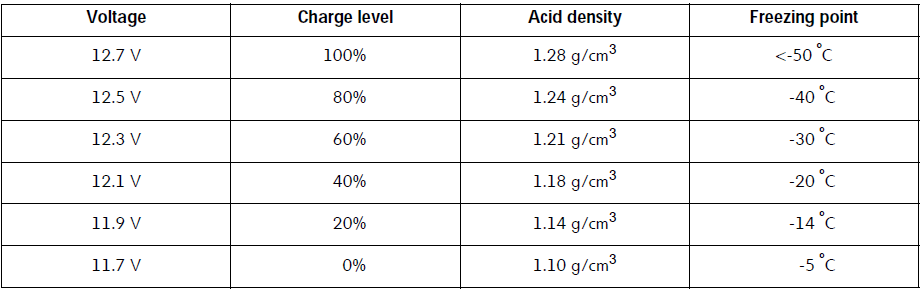
 1 pointCheers all, turns out it was crap replacement HT Leads which happened to affect the same cylinder!! Still, trip to my usual garage confirmed the issue and sorted that and the dicky oil pressure switch that had literally just started playing up and while they had it I got them to change the thermostat I was gonna do myself so all was good. No issues since, touch wood! Youngs Garage Gasoline Alley Wrotham 🤘😉👌1 pointOK, thanks for the reply. I did manage to connect the cable I got before and it did give me a fault code reading which said throttle body but that's as far as I could get. I don't know what the mechanic did other than he said he had cleaned it. I will give this a go though and see what happens and let you know. Lesley.1 pointIt's an Agm..its got the fabric cover and that is inside the plastic frame thing that the battery sits inside.👍1 pointA £350 or more difference on a 6-7 hour job is a lot of money, for some even a weeks earning splashed out. Based on the £1,100 quotes from Main Dealers and £750 ones. £1,300 is just really getting silly. But like most things, if you do not want the job quote high, and some might actually want the work done. There are likeky to be people with a 5 year old keeper that decide time to change the car rather than Timing belt, brake fluid change, maybe a DSG service or haldex and other stuff, Oil & Inspection Service and Extended Scope and another MOT. Buyers of a 5 year old or older 1.5 TSI ACT will need to be aware of the Servicing and Maintenance recommendations. ( Quoting a high price on a job you do not really want is like Asking Prices for cars when a trader actually wants to keep the car a while but it is part of the business.s inventory.) No free lunches in this life. That is the difference of one trained technician against another with the gear and more than ideas spending a good part of a day doing a job, parts, consumables & vat. Maybe the 2 year parts and labour warranty and a courtesy car and a nice waiting room is worth that extra money. Many will be paying that. Hopefully that is a fully trained and qualified person working on the car. Dealerships are going to be having longer waiting lists for slots in the workshop where a tech might be doing just 1 Timing Belt job and 4 services in a working day.1 point1 pointWell, either he doesn't know anything about cars, or he was lying to you This is a separate part. It might be moulded, but it's a part of external window seal, and can be replaced easily. Has nothing to do with whole window, except for the fact, that you need to remove the window to replace it. This is from different trim version, so not exactly yours, but should give you an idea of what i'm talking about. https://www.google.com/search?q=5E3837477&safe=active&rlz=1C1GCEA_en__1024AT1025&sxsrf=AJOqlzX7T3Xek9q74ETKOGIY3njpGI6v9g:1674655689442&source=lnms&tbm=isch&sa=X&ved=2ahUKEwjRwPXL8uL8AhWxs4sKHTLDCD4Q_AUoAnoECAEQBA&biw=2560&bih=1297&dpr=1#imgrc=kQ6pPP28cdq1VM According to ETKA, i think this is what you need: 5E3837475A Your has a different problem - seal is not peeling off, it's just installed incorrectly. Should be rather easy to fix, but takes time to get to it.1 pointFrom my prospective, I have zero interest in what anyone's labour rate is - they could charge £1 an hour for all I care. I also don't care what price they say or advertise at. What I do care about is the answer to my question - "In total, how much, including VAT, will the job cost me?" Perhaps I'm getting too old but in my experience there's usually, but not always, some element of robbing Peter to pay Paul about the final pricing. My local VAG specialist doesn't charge that much different than the main dealer for things like servicing. They do if you have an Audi tho 🤣1 pointIt's not super-clear to me why they need a ban, when they surely have the freedom to just not buy them? Some of the reasoning isn't daft tbh.1 pointAutoglym's Fast Glass, inside and outside. Awesome stuff. Spray on, wipe before it all flashes (ideally with a microfibre but kitchen towel will do) and it's job done.1 point1 pointNo not yet. My plan was to buy some time on Erwin and see if I could find the work shop manual but haven't had chance yet.1 point1 pointno, my car was bought second hand and it was one of the "assumed faults" that I managed to negotiate the price a bit. I am not happy about it but not unhappy enough to do something about it 😁1 point1 pointIf it only starts around 60mph, could it be a wind noise? Does it change according to revs or gears? Is it still there when you open windows? (possibly hard to confirm at 60!). Does it change on overrun, decelerating, braking, cornering? Gaz1 point1 pointHi toot, cheers. It’s only just passed 23k, should’ve said it was a DSG too. As far as the history is concerned I can’t put eyes on it right now!1 pointJust go to the obdeleven site and buy the white device if you have android https://obdeleven.com/en/home/10-obdeleven-device-0725423005103.html or the nextgen device if you have Apple https://obdeleven.com/en/home/187-stand-alone-0758277987851.html You will need to buy 10 credits as well in order to disable/lower the sound for the actuator. The instructions are good on the site and they have a live chat option as well. Once the device arrives, download OBeleven VAG from the google play store or apple equivalent, plug the device in and connect via bluetooth. It's an impressive app and no, i don't work for them:-)1 pointInteresting stuff and thank you (I've an engineering degree and so the sort of odd mind that finds this stuff interesting!) Cant do this until tomorrow as I am about and about for the rest of the day. Will do Thu morning and report back1 pointYour values seem a little low at 12.3V after a run. SOC State of Charge starts at 0% for 11.7V and 100% is 12.7V, so a 1V difference between empty and full What I would recommend is to charge again your battery, and check voltage at the end of the charge cycle directly on battery terminals. Then wait two hours, unlock car, open bonnet and again check voltage quickly, some control modules will be awake, but will give you a rough SOC. There are more things we can test, but this is where I would start. Take a read of these two SSP's to get you some useful background knowledge, and it might give you some ideas on what to test https://procarmanuals.com/pdf-online-vag-ssp-426-start-stop-system-2009/ https://procarmanuals.com/pdf-online-vag-ssp-504-vehicle-batteries/
 1 point1 point1 pointReally? - on a 2017 1.4TSI start/stop was standard on UK spec models. My previous 2015 1.4TSi definitely had start/stop, as does my current 2016 1.8TSI.1 point1 pointSadly Little good news out there for those waiting for PHEVs. Others may be having better luck. Anyone new here may not know about the delivery tracker. This is a spread sheet of orders and I encourage anyone with an outstanding order to add their details as it gives us all a better picture of whats happening. Whats getting delivered and whats not. https://docs.google.com/spreadsheets/d/17h4myLSMpZ3dohgDJX25mkOhKLbyepEaeEeYcA3AqFY/edit#gid=0 Cheers one and all.1 point1 pointI used the USB-c socket by the rear view mirror also. I had it hard wired into the previous car and it's so much easier to use the socket. One small cable, that's it.1 pointI know exactly how PCP works, tyvm. Given that the usual deposit required to order a car is £1k these days (used to be less!), that's how much I've put in as my deposit on the last couple of deals. I then pay £x/month until I get rid of the car. That works for me, and total amount paid is roughly equivalent to or less than leasing examples I've looked at for the same car / colour / spec (yes, you can get some very good lease deals if you're willing to be flexible on make / model / colour / spec, but that's the same with buying). It might have helped that I've always got a good deal that includes a low interest rate, making switching away from the PCP a bit pointless. Out of the 2 PCP deals I've completed with VWFS so far, I've handed the car back once (Octavia vRS) because it was worth less than the MGFV and the dealer through which I ordered my first Kodiaq didn't want to do trade-in (fair enough, really), and the second deal (my first Kodiaq) ended with a huge lump of equity thanks to the anomaly of used car prices rocketing skywards through the second half of 2021. So yes, the equity being greater than expected was a good thing - but it had absolutely nothing to do with the PCP deal. I even said in the post you quoted that it was down to good timing rather than anything else. PCP deals were originally designed so you would end up with equity - but because people concentrate on the headline £x/month figure, they soon changed so that the MGFV is as high as can possibly be so the £x/month is lower. I'd argue that this is a gamble on the part of the finance company, as if the car is worth less at the end, they're the ones that lose out, not the customer (well, assuming the customer hands the car back and doesn't trade it in with negative equity... but I guess some people probably end up doing that out of ignorance of the way it works). Also, I'd argue that PCP does benefit the customer - or, at least, a certain profile of customer. If you're wanting to buy a car outright and keep it for many years, then a PCP probably isn't the cheapest way of doing it (certainly not as interest rates get higher and higher) as you're probably paying more interest on the balloon amount than you would otherwise. However, if like me you enjoy (and are able to) a change of car every few years, then it's a simple way of doing that without having to worry about what the car is going to be worth - again, you have to understand how PCP works and use the correct option at the end of the deal, otherwise you can lose out big time. I'd argue that I've benefitted in different ways from the two deals I mention above, VWFS took the hit on the first car and I took the rewards on the second. This. I'd lease a car if I found exactly what I wanted for less money, but I never have. I don't intend on hanging onto cars for more than a few years, so PCP is just renting to me. If I end up with equity by any miracle (or anomaly!) then it's just a bonus that makes the payments on the next one a little bit less.1 pointBeen away from the forums for a couple of years and always found the members incredibly helpful. but I wasn't expecting the smart-arse responses on my first post for a while. Some people just can't keep their trap's shut and scroll on past.........1 point1 pointI like a quiet car without the raucous exhaust note, all a noisy exhaust does is attract the unwanted attention of the police and your neighbours. It's nice to have a sporty car without the attention of others.1 point1 pointIf it's the bolt I think you mean (attaches top plate to car body) they're M10x35. Parts diagram HERE.1 point

















Important Information
Welcome to BRISKODA. Please note the following important links Terms of Use. We have a comprehensive Privacy Policy. We have placed cookies on your device to help make this website better. You can adjust your cookie settings, otherwise we'll assume you're okay to continue.